Mike, a 34-year-old software tester in Chicago, was ready to buy a condo in Logan Square when his loan officer asked a question that stopped him cold: “What’s your debt-to-income ratio?” He knew his credit score. He had no idea what DTI meant.
If you’re wondering how to calculate your debt-to-income ratio, it takes one formula and about ten minutes. Let’s walk through Mike’s numbers together.
For educational purposes only. This is not financial, legal or tax advice. Mike is an illustrative example, and the figures are simplified.
What Is a Debt-to-Income Ratio?
Your debt-to-income ratio (DTI) is the percentage of your gross monthly income that goes toward monthly debt payments. Lenders use it as one way to see how much of your income is already committed before a new loan is added.
DTI is not part of your credit score. It is calculated separately, from your income and your debt payments.
The DTI Formula
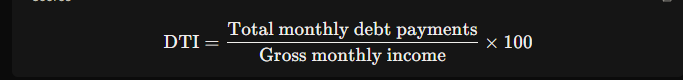
“Gross” means your income before taxes and other deductions come out.
Front-End vs Back-End DTI
Lenders often look at two versions:
- Front-end DTI: only your housing payment divided by gross monthly income
- Back-end DTI: your housing payment plus all other monthly debt payments, divided by gross monthly income
When people say “DTI” without more detail, they usually mean the back-end ratio.
Step-by-Step: Mike’s DTI Calculation
Step 1: Find your gross monthly income
Mike earns $78,000 a year before tax. That is $78,000 ÷ 12 = $6,500 per month.
Step 2: Add up your monthly debt payments
- Proposed housing payment: $1,950 (principal, interest, property tax and insurance of $1,800, plus $150 in condo HOA dues)
- Car loan: $420
- Student loan: $310
- Credit card minimum payments: $90
Total monthly debt payments: $2,770
Step 3: Divide and convert to a percentage
- Front-end DTI: $1,950 ÷ $6,500 = 0.30, or 30.0%
- Back-end DTI: $2,770 ÷ $6,500 = 0.426, or 42.6%
That is Mike’s debt-to-income ratio: 30.0% on the front end and 42.6% on the back end.
What Do Those Numbers Mean?
There is no single rule, because limits vary by lender, loan type and the rest of the borrower’s profile. These ranges are commonly cited as general reference points, not requirements:
- Below 36%: often viewed as comfortable
- 36% to 43%: frequently seen, and may get a closer look
- Above 43%: can be harder to qualify with, although some loan programs allow higher ratios when other factors are strong
Mike’s 42.6% sits near the top of the middle range. His lender also reviewed his credit history, savings, employment record and down payment. DTI is one piece of a larger file.
What Counts as Debt (and What Doesn’t)
Usually included:
- Your mortgage or proposed housing payment, including property taxes, insurance and HOA dues
- Car loans and student loans
- Minimum credit card payments
- Personal loans, child support and alimony
Usually not included:
- Utilities, groceries, phone and streaming bills
- Health and car insurance premiums
- Other everyday living expenses
In Illinois, property taxes can be a large part of a housing payment, so the tax portion is worth checking when you estimate it.
Common Mistakes When Calculating DTI
Using take-home pay. Mike’s first attempt used his net pay of about $4,900 a month and gave him 56.5%. He briefly panicked. The formula calls for gross income.
Forgetting HOA dues. Condo and association fees are often counted as part of the housing payment.
Using total balances. DTI uses the monthly payment on each debt, not what you owe in total.
Skipping small debts. Even minimum card payments belong in the total.
Skip the Maths: Use a DTI Calculator
You can run these numbers by hand, as Mike did, or enter them into a [INTERNAL LINK: /debt-to-income-ratio-calculator “debt-to-income ratio calculator”]. Changing one figure shows how each debt affects the result.
FAQ: Debt-to-Income Ratio
How do I calculate my debt-to-income ratio?
Add your monthly debt payments, divide by your gross monthly income, and multiply by 100. The result is your DTI as a percentage.
Is DTI the same as my credit score?
No. Your credit score reflects your credit history. DTI compares your debt payments to your income, and it does not appear on your credit report.
Does DTI include rent?
When a renter applies for a mortgage, lenders typically replace current rent with the proposed housing payment in the calculation.
Final Thoughts
Mike’s panic faded once he saw the real figures. DTI is just a fraction: what you pay each month on debt, compared with what you earn.
Once you know the formula and what belongs in it, the lender’s question becomes much less intimidating. For questions about a specific application, a licensed mortgage professional or a HUD-approved housing counselor can explain how a particular lender evaluates it.